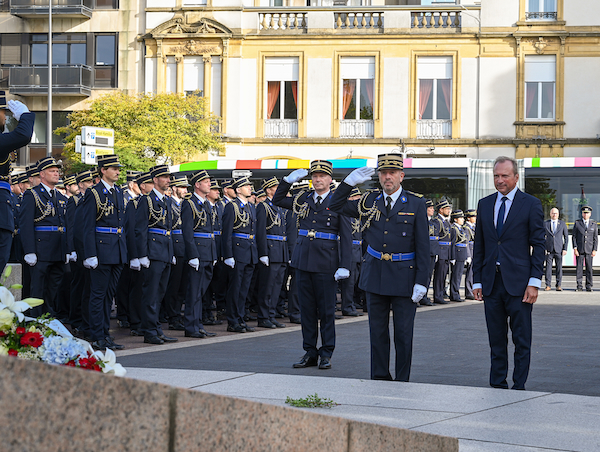
 (L–R) Stephan Chies, Deputy Director of the Customs and Excise Agency; Alain Bellot, Director of the Customs and Excise Agency; Gilles Roth, Luxembourg Minister of Finance;
Credit: ADA
On Friday 25 September 2026, Luxembourg’s Customs and Excise Agency (ADA) reported on the traditional celebration of the patron saint of customs officers, Saint Matthew, which took place on Monday 21 September.
The ADA reported that following the laying of a wreath at the foot of the “Gëlle Fra” Monument of Remembrance and a religious service at Notre-Dame Cathedral in Luxembourg, the College of the Mayor and Aldermen of the City of Luxembourg invited participants to a reception at the Cercle Cité.
In the presence of Gilles Roth, Luxembourg’s Minister of Finance, Kristian Vanderwaeren, Administrator-General of the Belgian Customs and Excise Administration, and numerous distinguished guests and prominent figures from public and political life, Alain Bellot, Director of the Customs and Excise Agency, addressed the customs officers in particular in a speech delivered for the occasion.
During his speech he stressed that, for the first time since 1968 and as a result of the fundamental reform of the Union Customs Code, the ADA is on the threshold of a genuine paradigm shift, affecting both its responsibilities and the organisation of its work.
The fundamental structural reforms to the Union Customs Code, introduced over the weekend of Saturday 19 to Sunday 20 September, require the Luxembourg administration to meet the challenge of fully assuming its European responsibilities in its day-to-day work. The ADA said that as a result the Saint Matthew celebrations were particularly symbolic this year, as the new Union Customs Code entered into force the previous day.
New Union Customs Code
Since the abolition of customs duties between the founding countries of the European Economic Community in 1968, which subsequently became the European Union (EU) Single Market in 1993, the Union Customs Code has undergone its most fundamental reform. The scale of the changes is such that it is appropriate to refer to it as a new Union Customs Code (nUCC).
European Union Customs Authority (EUCA)
One of the key innovations of the nUCC is the establishment of the European Union Customs Authority (EUCA).
This decentralised European agency is headquartered in Lille. Its responsibilities include managing the future EU Customs Data Hub, analysing risks associated with flows of goods from third countries, providing operational support to the customs authorities of the 27 Member States and managing crises.
EU Customs Data Hub (EUCDH)
The second central element is the EU Customs Data Hub (EUCDH). This centralised platform will replace the 111 existing IT systems and interfaces, simplifying procedures for both businesses and customs authorities.
Economic operators will benefit from a single access point for all their customs formalities in the EU. Commercial data submitted in real time by businesses to the EUCDH will enable customs authorities to monitor supply chains continuously and in real time, while also facilitating exchanges between the customs administrations of the Member States and the EUCA.
The development of the EUCDH will take place in stages. From 1 July 2028, distance-selling businesses that use the Import One Stop Shop (IOSS) for VAT purposes will have to submit commercial data via the EUCDH. In 2034, the use of the EUCDH will become mandatory for all economic operators.
The reform also aims to make online platforms facilitating distance sales, as well as businesses supplying goods from third countries in connection with such sales, more accountable. These entities will be considered importers if they are established in the EU. Otherwise, platforms and businesses must appoint a customs representative in the EU who is prepared to assume joint and several responsibility for the tax and non-tax compliance of imported goods.
Union Handling Fee (UHF)
From 1 November 2026, the nUCC will introduce a Union Handling Fee (UHF) for all distance sales of goods originating in third countries, regardless of their value.
The flat-rate fee of €2 will be levied per identical item, meaning each item of merchandise with the same customs tariff classification. The revenue generated will contribute to the costs of activities related to customs supervision by the customs authorities of the 27 Member States and the EUCA, as well as to the management of the EUCDH.
The UHF is separate from the flat-rate customs duty of €3 levied on each identical item:
|
|
Flat-rate customs duty |
Union Handling Fee |
|
Date of application |
Since 1 July 2026 |
From 1 November 2026 |
|
Application per item |
Distance sales consignment ≤ €150 |
Distance sales regardless of consignment value |
|
Amount |
€3 |
€2 |
This means that, for distance sales originating in a third country where the value of the consignment does not exceed €150, the €3 flat-rate customs duty per item will be supplemented by a €2 UHF, resulting in a total of €5 payable per imported item.